
What are the possible types of articles of incorporation?
In France, there are several legal structures that allow institutions to hold other people’s money; all are authorized and regulated by the Prudential Supervision and Resolution Authority (ACPR), which operates under the auspices of the Bank of France.
The difference between a bank and a payment institution lies primarily in the fact that each is authorized to make money from the funds entrusted to it. A bank, or credit institution, accepts deposits, grants loans, and processes payments. A payment institution processes payments and maintains payment accounts, without lending out the funds entrusted to it.
An electronic money institution offers the same services and can also issue electronic money-such as that used in prepaid cards or online wallets.
In addition to these three types of entities, agents and distributors act on behalf of an authorized institution. Many consumer apps operate this way: the brand belongs to the app, while liability rests with the partner institution.
What is the difference between a bank and a payment institution in terms of the protection of funds?
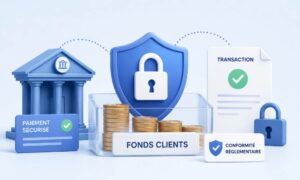
The difference between a bank and a payment institution lies in how the money entrusted to them is used. A bank lends it out, which is why a guarantee fund covers deposits up to 100,000 euros per customer per bank. A payment institution or electronic money institution does not lend it out: it must segregate it-that is, hold it in dedicated accounts separate from its own.
In the event of the institution’s failure, these funds are not part of its assets. They are returned to customers without being subject to distribution among creditors.
How do I check an actor’s status?
The legal notices of a licensed institution indicate its status and license number. The official registry of financial intermediaries (REGAFI), which is available online and free of charge, allows you to verify this information, and the blacklists published by the ACPR and the Autorité des marchés financiers identify unauthorized entities.
CentralPay, for example, is an electronic money institution authorized by the ACPR under license number CIB 17138, which can be verified in the registry.
As a business, what questions should you ask your payment service provider?
A company can first ask its service provider whether it is itself a licensed institution or an agent of another institution, where its clients’ funds are held, and how long it takes for those funds to be paid to the company.
She can also verify that it is PCI DSS-certified-the data security standard for credit cards-and that its activities fall within the scope of its terms of use.
Is a payment institution less secure than a bank?
It is protected in a different way, and that is where the difference between a bank and a payment institution matters most for your funds. A bank lends out its depositors’ money, which is why a deposit insurance fund covers these deposits, up to 100,000 euros per customer per bank. A payment institution or electronic money institution does not lend out its customers’ money. It must segregate it: keep it in dedicated accounts, separate from its own.
Pourquoi les établissements de paiement se spécialisent-ils ?
La réglementation européenne a créé ces statuts pour ouvrir les services de paiement à d’autres acteurs que les banques. Beaucoup d’établissements se sont construits autour de besoins précis des entreprises : encaisser pour le compte de tiers, gérer des acomptes et des soldes, verser à plusieurs bénéficiaires ou rapprocher automatiquement un paiement de la commande qu’il règle.
Some have specialized by industry, because a debt collection agency, a reservation center, and a dealership network handle payments differently.
For a company, the first question is always who keeps the money; the second is whether that partner understands the challenges of the business.
About CentralPay
CentralPay is an electronic money institution authorized by the ACPR (CIB 17138), with offices in Tours and Paris.
Its payment platform is designed for industries where payment collection falls outside the standard framework: debt collection agencies, travel booking platforms, distribution networks, and marketplaces. It supports down payments and final balances, third-party funds, payments to multiple recipients, and automatic payment reconciliation.
More than 200 companies entrust their collections to it, with more than 2.5 billion euros in payments processed.